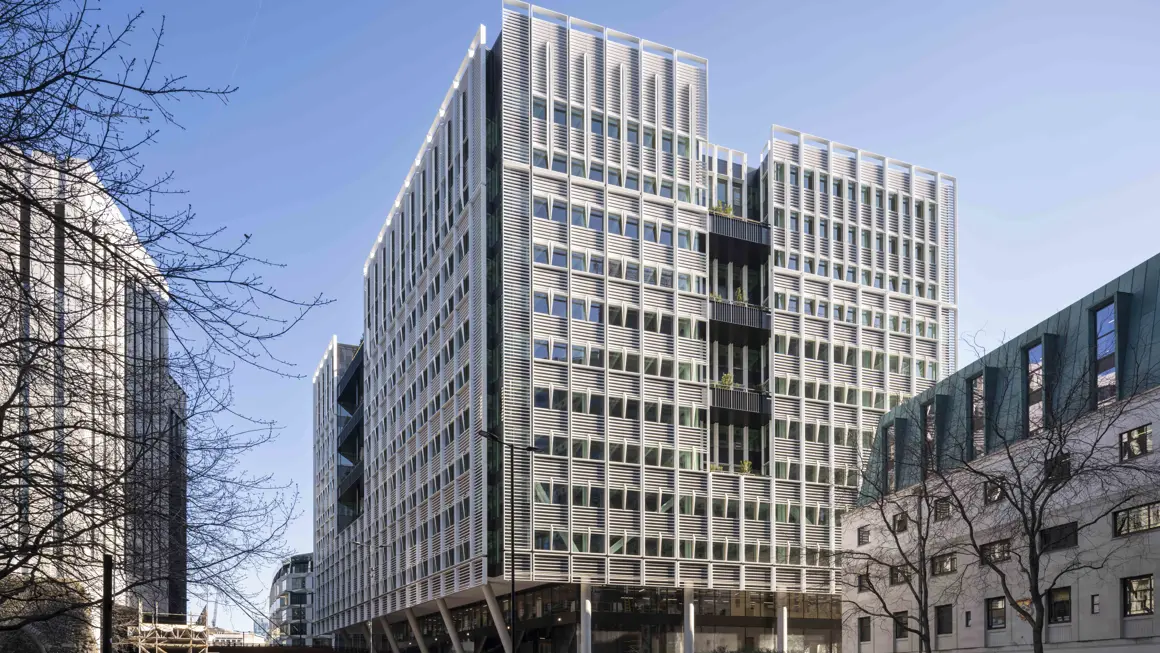
Office leasing activity in London hit a two-year high in Q3 2026, according to the latest data from Cushman & Wakefield.
The company’s Central London Offices Marketbeat found that take-up reached 3.08m sq ft in the quarter – a 25% increase on the previous quarter and 24% ahead of the five-year average.
The City reclaimed the top spot for the largest market share in Q3, with 1.85m sq ft of activity recorded. The West End recorded activity of 1.05m sq ft with the remaining 176,000 sq ft leased in East London.
Take-up in the first nine months of the year rose to 7.46m sq ft – up 11% year-on-year. The banking and finance sector was the most active in the quarter, replacing technology which was the most dominant sector at the half-year mark.
The volume of space under offer remained high at 4.41m sq ft – 42% above the five-year quarterly average.
On the investment front, £2.13bn of office assets were traded across the central London office investment market in Q3, representing an increase of 4% on the previous quarter.
UK purchasers have accounted for 46% of investment in the year so far compared with 31% in 2025. Overseas investors are the dominant investor type for larger lots, with 73% of the number of deals of more than £100m in 2025 coming from overseas capital and 65% of deals so far in 2026.
Rory Paton, co-head of City agency at Cushman & Wakefield, said: “The increase in leasing activity points to a market where occupiers are showing greater conviction and moving decisively when the right opportunities arise. Demand remains firmly focused on best-in-class buildings and with much of the future supply already committed, competition for the highest-quality space is set to intensify.”
Chris Bennett, international partner and head of London offices capital markets at Cushman & Wakefield, added: “UK investors are investing heavily and are showing renewed confidence in the London office market, particularly for small and medium lot sizes. Despite a relative slowing in overseas capital, they remain the dominant buyer of larger lot sizes of over £100m.
“Demand remains strong and, with £4.41bn of assets awaiting completion, there are positive news stories for the market, and notwithstanding any significant macro shocks, this should carry through over the short-to-medium term. Although the recent rate rise saw the start of the rate tightening cycle, this was already priced into market rates and should not impact on transactional activity.”